Markets
IMF's Georgieva tells governments the free ride on debt is over
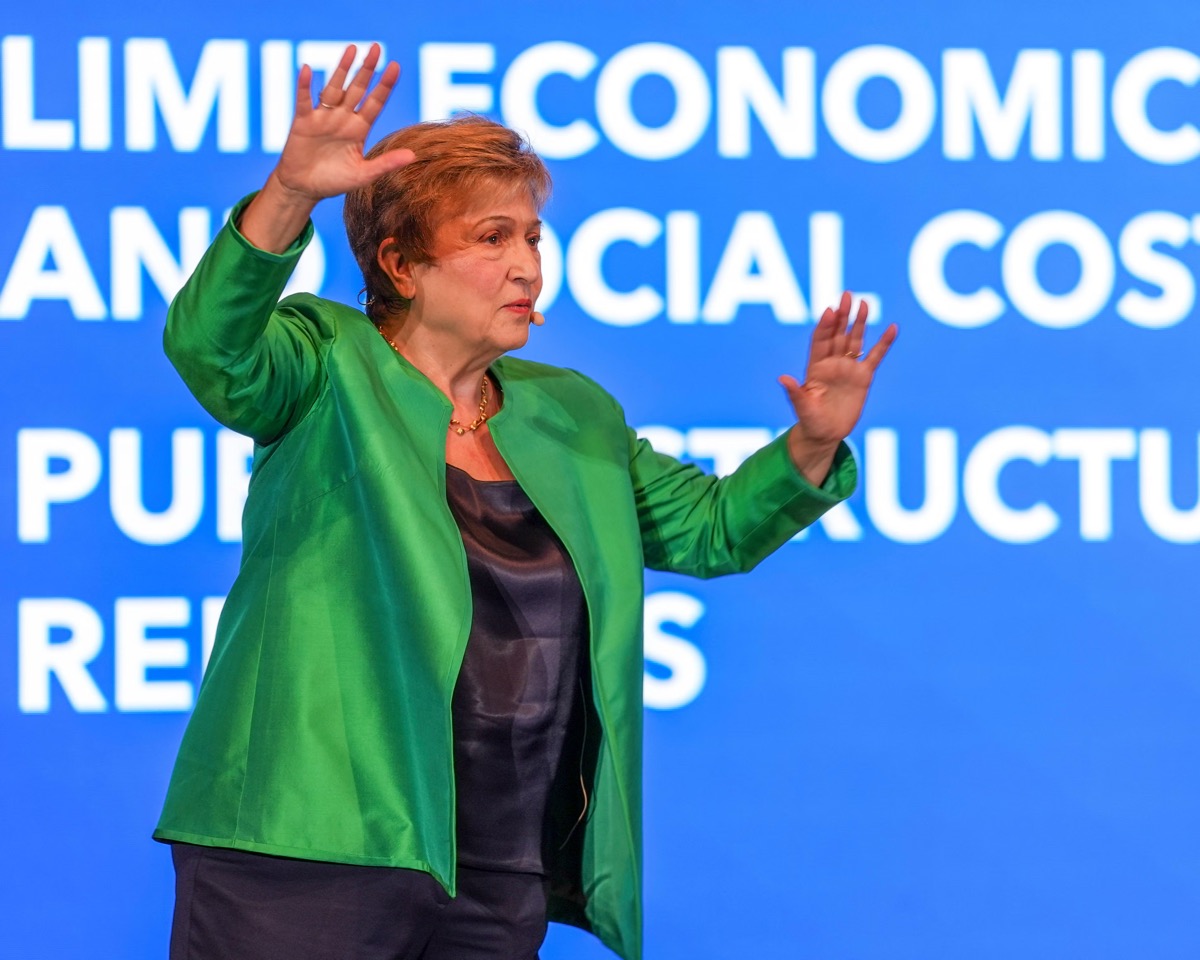
Speaking in Singapore ahead of the IMF and World Bank's annual meetings, Kristalina Georgieva told governments plainly that growth alone will not fix their balance sheets anymore. Global public debt is closing in on 100 percent of GDP, bond yields are at multi-decade highs, and the IMF's message has shifted from warning to deadline.
Kristalina Georgieva used a speech in Singapore ahead of the IMF and World Bank's annual meetings in Bangkok to deliver one of her bluntest warnings yet on the state of government balance sheets worldwide. Global public debt is on track to exceed 100 percent of GDP before the end of the decade, a level last seen in the aftermath of the Second World War, and the IMF's managing director made clear that the institution no longer sees faster growth as a realistic way out. Her phrasing was direct: governments can no longer rely on higher growth rates alone to solve fiscal problems.
Why borrowing costs changed the equation
For 17 years, Georgieva noted, policymakers benefited from an environment where interest rates sat below GDP growth, a condition that let debt loads grow without becoming unmanageable. That environment has ended. Benchmark sovereign bond yields have surged to levels not seen in decades: US 10 year yields are at their highest since 2007, Germany's since 2009, and Japan's since 1996. When borrowing costs exceed growth rates, the arithmetic of debt sustainability flips, and every additional dollar borrowed becomes harder to grow out of rather than easier.
- Global public debt is projected to exceed 100 percent of GDP before 2030, the highest level since World War II.
- Global debt overall has exceeded 365 trillion dollars, according to the Institute of International Finance.
- US 10 year Treasury yields are at their highest level since 2007.
- German 10 year bund yields are at their highest since 2009, Japanese yields since 1996.
- Oil is trading near 100 dollars a barrel, above the 89 dollar benchmark the IMF assumed for its 2026 forecasts.
- The IMF forecasts 3 percent global growth in 2026 and 3.4 percent in 2027.
Three pressures hitting the global economy at once
Georgieva framed the moment as the convergence of three distinct pressures rather than a single crisis. The first is the uneven boom in artificial intelligence investment, concentrated in a handful of economies and carrying real upside, with the IMF estimating AI could add up to half a percentage point to global growth annually, roughly equivalent to adding an economy the size of ASEAN over a decade. The second is persistently elevated energy prices, with disruptions tied to conflicts in the Middle East and Ukraine expected to continue through 2027 and AI infrastructure itself adding to energy demand. The third, and the one she spent the most time on, is the debt burden itself, now large enough that advanced economies in particular are, in her words, crying out for fiscal space to be replenished.
“We have been warning that fiscal consolidation must take place, and we are seeing a lot of understanding, but not enough action.”
What the IMF wants governments and central banks to do
The prescription Georgieva laid out has two parts. On the fiscal side, she called for credible medium term consolidation plans from heavily indebted advanced economies, a polite way of saying spending discipline and higher taxes, since growth alone is no longer sufficient. On the monetary side, she backed a prudently hawkish bias from central banks, explicitly describing recent rate decisions from the Federal Reserve, the European Central Bank and the Bank of Japan as highly appropriate given inflationary pressures from AI driven demand, energy costs, tariffs and defence spending. That combination, tighter fiscal policy paired with tighter monetary policy, is a harder mix for governments to sell to voters than either alone, which is likely why she described seeing understanding but not enough action so far.
Our reading
Three things stand out. First, the shift in IMF language from warning to something closer to a deadline, debt nearing 100 percent of GDP by decade's end, reflects how little room is left for the institution's usual diplomatic hedging, and it signals the Fund expects this to dominate discussion at the Bangkok meetings rather than remain background noise. Second, naming the US, Germany and Japan's bond yields specifically is a deliberate choice, since those three sit at the centre of the global financial system, and multi-decade high borrowing costs there ripple through every other country's financing costs as well. Third, acknowledging AI's real growth upside in the same breath as the debt warning shows the IMF is not simply pessimistic, it is trying to separate a genuine structural opportunity from a genuine structural risk and asking governments to capture the first while addressing the second, rather than letting AI driven optimism paper over the debt problem. We read Georgieva's speech less as a routine fiscal lecture and more as the clearest signal yet that the era of borrowing cheaply against future growth has ended, and that the next phase of global fiscal policy will be shaped by how quickly, and how painfully, governments adjust to that.
Topics